 By
| CONTRACT | CLOSE | NET CHANGE |
|---|---|---|
| Dec '26 Corn | 528 1/4 | +3/4 |
| Mar '27 Corn | 542 | +1/2 |
| Nov '26 Beans | 1319 | +1 1/2 |
| Jan '27 Beans | 1332 1/2 | +1/2 |
| Dec '26 Chi Wheat | 703 1/4 | -3 3/4 |
| Dec '26 KC Wheat | 762 | -5 |
| Dec '26 Cotton | 82.60 | -.71 |
| Crude Oil (spot futures) | 92.41 | -2.20 |
| US Dollar Index (spot futures) | 100.765 | -.21 |
| Dow Jones (spot futures) | 52,163 | +446 |
Daily Glance
Xi's last day in Washington started with our markets washing out overnight, as the summit wrapped up with nothing new on ag purchases. Corn was down better than a dozen cents at its worst and beans off about 20.
Want the rest of today's comment?
Leave your name and email to read the full daily market comment, including technicals, weather and trade implications.
Both spent the rest of the session grinding back, and by the close they had erased all of it and then some, each finishing higher and within a couple cents of the day's high.
Wheat had the roughest go of it, trading more than 23 cents lower and dipping well under $7.00 before cutting that loss down to a few cents by the close.
It wasn't only the summit weighing on things overnight. Turkey, Egypt and others renewed their push to reopen a Black Sea grain corridor, which Russia has turned down before, and reports circulated that Iran had offered to reopen the Strait of Hormuz on its own terms, which President Trump rejected.
On the summit itself, President Trump said farmers will be very happy with how the meetings went. Ambassador Greer said the two sides agreed on which goods, farm products included, will be shielded from future tariffs and trade disputes, though nothing new on purchases came out of it.
Outside markets were mixed. Crude gave back better than two dollars of its recent climb, the dollar index slipped, and the Dow tacked on better than 400 points.
Key Points/Developments
Technicals: December corn traded down to 514 3/4 overnight, a quarter cent under the 515 we talked about yesterday, then turned and never looked back, settling at 528 1/4 and just off its high. That keeps the 525 area as first support, with today's low near 515 under it and the 50 day average down around 500.
Resistance is unchanged, with the 535 area first, then Tuesday's high of 544 1/2 and the contract high at 550.
November beans broke last Friday's low of 1300 overnight, trading to 1297 1/2 before recovering to close higher at 1319. The 1310 area is first support again, with today's low near 1297 and the 1280 area below that.
The 1332 area, which has turned beans back three times this month, is still the resistance to beat.
Spreads: The Dec/Mar corn spread narrowed a quarter cent to 13 3/4. The Nov/Jan bean spread narrowed a penny to 13 1/2, with western belt processors still having to reach for bushels while harvest there sits in the mud.
Weather: TStorm made no changes today, leaving corn and soybeans at neutral and winter wheat at slightly favorable.
It has moved partway toward the wetter models we mentioned yesterday. TStorm now has 1 to 4 inches for Iowa and Missouri Monday through Wednesday, and Illinois goes from a light chance to 1 to 2 inches later in the week, with some flooding likely in and near Iowa and harvest slowing just about everywhere late next week.
What keeps TStorm away from the wet and expensive harvest story is what comes after, with a much drier and cooler stretch likely to follow. The eastern belt also gets a two or three day window to run before the rain arrives.
In South America, rain within the week should help Argentina's corn, which is about half planted, and get central Brazil's soybean planting going.
Markets/Trading Implications
Support held today, and that is about as much as we would take from it. The bounce off the overnight lows says there are still buyers willing to step in down there, at least for now.
What we still don't have is any clarity on China. The meetings wrapped up without a number attached to any of it, and an agreement to shield farm goods from future tariffs is not the same thing as somebody showing up to buy. Until that changes there are more unknowns in this than we'd like.
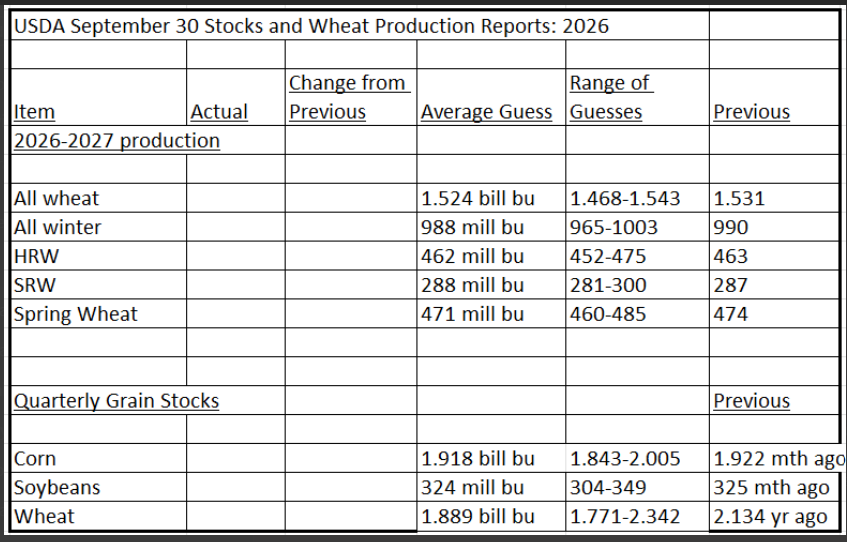
Wednesday's quarterly stocks report is the next real piece of information we get. Soybean basis has been awfully firm for this far into harvest, and the bulls are hoping the stocks number is what finally explains it. We wouldn't hang too much on that ahead of time, but it's the one to watch.
Call anytime.
Other Notes
- For the week, Dec corn gained 3/4 of a cent, Nov beans gained 15 1/2 cents, Chicago wheat lost 11 cents, and cotton gained 1.47.
- After the close, Iran said the reports of talks with the United States are false and were meant to influence markets. Whatever comes of that, this market keeps trading the headlines harder than anything actually happening on the ground.
- Russia and Ukraine traded drone and missile strikes again overnight, with more of the damage landing on farm and energy infrastructure. Even if the fighting stopped tomorrow, it would take months of repairs before Black Sea grain moved normally again.
- Wednesday brings on the quarterly stocks report. Below is a summary of the average trade guesses:
Static Notes
- Commitment of Traders data covering positions through Tuesday, September 22, showed the funds moving back into beans while trimming corn. Corn's net long came down 12k to 414k. Soybeans' net long grew 20k to 265k, and wheat's net short deepened from nearly 5k to 13k.
- Prices during the corresponding week saw December corn gain 1 cent, November beans gain 6 3/4, and December Chicago wheat lose 11 1/4. In the three trading days since this report, corn has lost 8 1/2 cents, soybeans have lost 6 1/2, and Chicago wheat has lost 14.
Have a great weekend!
Clayton and Taylor
RISK DISCLAIMER:
Trading in futures products entails significant risks of loss which must be understood prior to trading and may not be appropriate for all investors.
Please contact your account representative for more information on these risks. Past performance of actual trades or strategies cited herein is not necessarily indicative of future performance.