 By
| CONTRACT | CLOSE | NET CHANGE |
|---|---|---|
| Dec '26 Corn | 533 3/4 | +6 |
| Mar '27 Corn | 549 1/4 | +6 |
| Nov '26 Beans | 1332 1/4 | +22 3/4 |
| Jan '27 Beans | 1347 1/4 | +22 |
| Dec '26 Chi Wheat | 741 1/4 | +12 1/2 |
| Dec '26 KC Wheat | 818 3/4 | +12 1/2 |
| Dec '26 Cotton | 88.20 | +0.92 |
| Crude Oil (spot futures) | 102.61 | +6.57 |
| US Dollar Index (spot futures) | 99.08 | +0.30 |
| Dow Jones (spot futures) | 52,082 | -345 |
Daily Glance
We were set up for a quiet positioning day ahead of tomorrow's report and that is not what we got. The energy complex took off and pulled our markets along with it, beans doing most of the work while corn and wheat followed.
Want the rest of today's comment?
Leave your name and email to read the full daily market comment, including technicals, weather and trade implications.
Beans finally broke out of the 30 cent range that has held them the last nine or ten days, taking out last week's high early and trading up to roughly 1334 at their best before easing a little into the close. Corn made back everything it gave up yesterday and then some, wheat put together its best session in a couple of weeks, and cotton added most of a dollar of its own.
China stayed at the table as well, with another good sized purchase that puts them over 40 million bushels of beans bought just since last Friday.
Crude was the real story though, up better than six and a half dollars to its highest level since May. Word that the conflict with Iran could run into November and inventories that keep shrinking were behind the move. The dollar firmed a touch and the Dow gave back a piece of yesterday's ground.
Key Points/Developments
Technicals: Dec corn added 6 cents to 533 3/4, making back all of yesterday's loss and then some. The 527 to 530 support zone we flagged yesterday did its job and stays the first line underneath, with the 50 day average near 510 below that. Resistance is unchanged at 540 to 542, then 550.
Nov beans jumped 22 3/4 cents to 1332 1/4, taking out the 1321 to 1324 resistance we have been calling the top of the range and closing well through it for the best close of this move. That old resistance becomes the first support now, then 1300 to 1306 underneath. Next resistance is the 1340 we flagged yesterday, which today's high fell just short of.
Spreads: The Dec/Mar corn spread held at 15 1/2 cents, unchanged again. The Nov/Jan bean spread narrowed to 15 cents from 15 3/4, the first real tightening in that carry in a while, which is worth watching if beans keep working higher.
Weather: TStorm made no changes today, leaving corn and soybeans both at neutral and winter wheat at slightly unfavorable after yesterday's downgrade. The heat across the middle of the country winds down over the next 5 to 10 days as a series of cool fronts come through with pockets of rain and thunderstorms, which should help soil moisture for winter wheat planting later this month.
Southern Brazil keeps getting wetter for its first corn and wheat, with 44 percent of that wheat crop already wetter than normal over the last 30 days and the share climbing through mid month.
TStorm's monthly El Nino update also came out today, and it has the strongest event on record probably underway, peaking around December before weakening quickly over the first half of next year. Two pieces of it matter to us directly.
Markets/Trading Implications
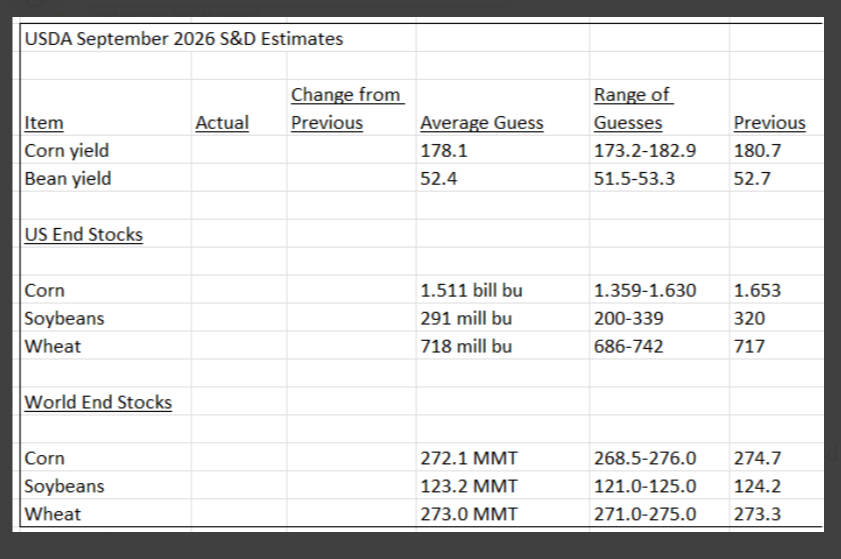
The whole trade is pointed at a yield number tomorrow, 178.1 on corn and 52.4 on beans, with the corn guesses running nearly ten bushels wide against a much tighter spread on beans. Our lean is that the 178 does not print, both because of USDA's history with it and because TStorm and StoneX are carrying higher numbers.
Yield is only one line on the page though, and we would not be shocked to see the surprise come from somewhere else entirely. Harvested acres are still an open question with as much corn as went for silage this year, old crop ending stocks and the feed and residual number behind them are due a hard look, and the export line can move either direction.
The ending stock guesses tell you as much as the yield guesses do, running from 1.359 to 1.630 billion bushels on corn and anywhere from 200 to 339 million on beans. That is a wider argument than the yield spread, and it is the sort of line that moves a market without anybody having predicted it.
On the yield itself, we said yesterday that a 178 would be bullish in our eyes and we still think that, since it takes a real bite out of last month's 180.7. A print back up around 180 would say the crop did not shrink the way everyone assumed.
Bullish and lasting are two different things though. We think it takes 177 or below on corn, or something near 51.5 on beans, before we would expect a rally that really goes, and short of that, with the funds as long as they are and a market this stretched at this time of year, we have a hard time seeing it explode and not look back.
The flip side is that the length itself can do the work. Funds will push prices higher without much help from a report, partly to defend what they own and partly to find a window to move those bushels into weaker hands.
So we would look for either a surge to new highs hunting sell stops or simply a lower trade, and given where prices already sit we probably need something friendly just to hold this ground. What we do not expect is the downside getting away from us.
Some of that confidence is macro, and the common read on it has things backwards. Money is not leaving the bond market because yields went up, it is leaving because inflation is expected to outrun what a bond pays, and it has to land somewhere that keeps up.
Bottom line, we think extreme moves in either direction get faded for the time being.
Other Notes
- Another 479,000 metric tons of soybeans sold to China and unknown destinations this morning, which puts sales over 40 million bushels since last Friday and keeps China on pace for its 25 million tonne commitment level.
- Both sides are said to be hoping for an agreement on reduced reciprocal tariffs covering 30 billion dollars of goods, with President Xi's September 24 visit to Washington the likely venue.
- Russia shipped just 170,000 tonnes of wheat in the first eight days of September, only 50,000 of that in the last four days, and September export estimates are sliding toward 700,000 to 900,000 tonnes against 4.6 million a year ago.
- The table below carries the average trade guesses for tomorrow's report alongside the range of estimates and last month's figures.
Static Notes
- Commitment of Traders data covering positions through Tuesday, September 1, showed funds still adding aggressively. Corn's net long grew to about 431,000 contracts, up roughly 55,000 on the week, funds buying about 28,000 new longs and covering another 27,000 of shorts. Soybeans' net long grew to about 241,000, up roughly 43,000, while wheat flipped from a net short of about 14,000 to a net long of about 15,000, its first net long position since late April.
- Measured against the September 1 closes that report captured, six sessions later corn sits 12 1/4 cents lower and Chicago wheat 41 1/4 lower, while beans have not only made all of it back but are 14 1/2 cents higher. A fresh report covering positions through September 8 should be out tomorrow afternoon.
Have a nice evening!
Clayton and Taylor
RISK DISCLAIMER:
Trading in futures products entails significant risks of loss which must be understood prior to trading and may not be appropriate for all investors.
Please contact your account representative for more information on these risks. Past performance of actual trades or strategies cited herein is not necessarily indicative of future performance.